A CBP Form 28 is a formal Request for Information issued when U.S. Customs and Border Protection needs additional facts or documents to evaluate an import entry. For a DDP shipment, the importer of record must control the response even when the seller, freight forwarder, customs broker and overseas factory each hold part of the evidence. The safest approach is to identify every question, assign a document owner, reconcile the response to the filed entry and submit a complete, certified package through the channel and deadline shown on the notice.
Preserve the notice and entry file, record the response deadline, notify the importer’s customs broker and responsible compliance manager, and stop informal changes to the underlying documents. Build a question-by-question response supported by transaction records, product evidence and clear calculations. If a fact in the entry may be wrong, obtain qualified customs advice before deciding whether a correction, prior disclosure or other procedure is appropriate.
Form 28 is not the same as a cargo hold or a penalty notice. It is an information request, but the answer can influence classification, customs value, origin, trade-program eligibility, admissibility and future entries. A weak or inconsistent response may be followed by a CBP Form 29 Notice of Action .
- Confirm the notice and deadline: Retain the complete Form 28, receipt date, response instructions and assigned CBP contact.
- Identify the importer of record: Verify the entry summary, importer number, broker power of attorney and internal response authority.
- Freeze the entry evidence: Preserve original invoices, purchase orders, payments, packing, transport and product records before any correction.
- Map every question: Track each request, answer, exhibit, open issue and accountable owner in a response matrix.
- Review related entries: Identify other shipments using the same product, supplier, classification, value, origin or program claim.
CBP Form 28 is provided for under 19 CFR 151.11. The current form identifies the entry, merchandise, tariff item, country of origin or exportation, broker and parties, then lists the questions or items CBP wants. The form includes common requests for contracts, purchase orders, descriptive literature, component or ingredient breakdowns, samples and transaction-cost details such as packing, commissions, proceeds, assists and royalties.
The request may result from an entry review, a compliance concern, a product verification, a trade-agreement claim, a valuation question or an admissibility inquiry. It does not automatically mean CBP has decided the entry is wrong. It does mean the existing entry package did not provide enough information for the determination being made.
Under DDP, the commercial seller may coordinate freight, customs clearance and delivery, but U.S. customs responsibility follows the importer-of-record structure—not the marketing label on the quotation. The broker may have filed the entry, while the factory holds production records, the seller holds price and payment records, and the U.S. buyer holds product-use information. These records must tell one coherent story.
Settle party responsibilities using the guide to importer of record, consignee and customs broker roles . The broker can transmit or organize a response, but should not be expected to invent manufacturing facts or certify records it does not own. Likewise, a foreign seller should not answer in the importer’s name without proper coordination and authority.
Build a Question-by-Question Response Matrix
Start with a matrix instead of drafting a long letter. Copy each numbered question or requested item exactly enough to preserve its meaning. Add columns for the responsible owner, the proposed answer, supporting exhibit, open issue and approval status. This structure exposes missing evidence before submission and makes the final package easier to review.
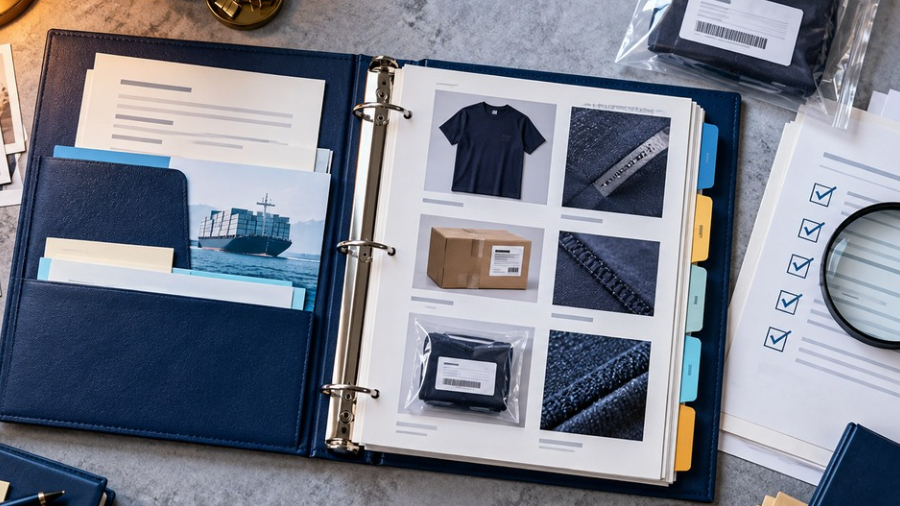
- Classification: Use technical sheets, photographs, composition, dimensions, function, operating method and exact-product samples.
- Transaction value: Reconcile the purchase order, invoice, payment, contract, price list, credits and related-party information to the entry.
- Assists and royalties: Provide tooling, design or license records plus a reproducible allocation method, currency and period.
- Country of origin: Support the governing origin rule with bills of materials, production flow, factory and sourcing records.
- Trade preference: Confirm the certification, supplier declarations and qualification calculations cover the exact goods and entry period.
- Admissibility: Match permits, registrations, test reports, agency data and product identifiers to the model, lot, facility and shipment.
Reconcile the Response to the Filed Entry
Before answering, compare the supporting records with the CBP Form 7501 or ACE entry-summary data . Confirm importer identity, manufacturer, seller, buyer, country of origin, tariff classification, entered value, quantity, duty rate and special-program indicators. A response that answers the question but conflicts with another entry field may create a new issue.
For value questions, use the DDP customs-value guide to separate international freight deductions from additions such as assists, packing, certain royalties and proceeds. Do not submit a new invoice merely because the filed invoice is inconvenient. Preserve the original record and explain any legitimate correction transparently.
Documents Should Be Authentic, Traceable and Explained
A large attachment set is not necessarily a strong response. Each exhibit should have a clear source, date, transaction link and purpose. Translate relevant foreign-language records accurately. Explain codes, abbreviations and relationships between companies. If a spreadsheet calculates an allocation, include the source figures and method rather than only the result.
The current Form 28 contains a certification that the information furnished is true and correct and that any samples were taken from the covered shipment. Determine who is authorized to sign for the importer and who has personal or corporate knowledge of the response. The customs broker’s role and power of attorney should be reviewed using the customs power-of-attorney checklist .
What If the Entry May Be Incorrect?
Do not hide the inconsistency, overwrite source records or send a speculative answer. First determine the scope: one line, one entry, one supplier period or a recurring control failure. Separate facts already supported by records from conclusions that require legal or technical analysis. Ask the broker or customs counsel whether a post-summary correction, protest, prior disclosure or another procedure is available and appropriate for the entry’s status.
A Form 28 response and a corrective filing solve different problems. The response supplies requested information; a correction changes entry data through an authorized mechanism. Coordinate them so that dates, calculations and explanations agree.
Common Response Failures
- Forwarding the notice without ownership: every party assumes someone else is preparing the answer.
- Answering with conclusions only: statements such as “the code is correct” are submitted without product facts or legal analysis.
- Using unrelated product evidence: brochures or samples cover a different model, material or production period.
- Ignoring valuation additions: tooling, design, royalties, packing or seller proceeds are not addressed.
- Submitting conflicting records: invoice, purchase order, payment and entry data identify different prices or parties without explanation.
- Missing foreign records: the importer waits until the final days to request factory and supplier documents.
- Failing to review other entries: a recurring issue remains uncorrected after the response is filed.
- Treating silence as acceptance: the team closes the matter without monitoring later CBP communications.
- Log the notice, entry number, issue, CBP contact, receipt date and stated deadline.
- Notify the importer’s compliance owner, broker and necessary legal or technical advisers.
- Preserve the filed entry and original commercial, payment, transport and product records.
- Convert every request into a response-matrix line with one accountable owner.
- Collect exact-product evidence from the seller, manufacturer and internal systems.
- Reconcile each fact to the entry summary and DDP commercial invoice .
- Identify inaccuracies, affected entries and available correction procedures.
- Draft a concise cover letter and indexed exhibits that answer the questions in order.
- Obtain factual, customs and authorized-signatory review before submission.
- Submit by the method shown on the notice and retain proof of delivery.
- Monitor for follow-up questions, Form 29 action, liquidation or broader entry review.
- Convert the issue into a preventive control for future DDP shipments.
Response Package Checklist
- Complete Form 28 and all continuation pages are legible.
- Entry, importer, product and deadline have been independently verified.
- Every question is answered or clearly identified as not applicable with a reason.
- Each factual statement points to a numbered exhibit.
- Calculations can be reproduced from attached source records.
- Translations identify the original record and translator or method used.
- Confidential commercial information is handled through the appropriate channel.
- The response is consistent with invoice, payment, transport and entry-summary data.
- The signer is authorized and understands the certification.
- Submission evidence and a complete duplicate file are retained.
Frequently Asked Questions
Is CBP Form 28 a penalty?
No. It is a request for information, not a penalty assessment. However, the facts disclosed—or not disclosed—can affect duties, admissibility, liquidation, enforcement decisions and future entries.
Can the customs broker answer Form 28 for the importer?
A properly authorized broker may help prepare and transmit the response, but the importer must ensure that the facts and certification are accurate. Manufacturing, pricing and origin evidence often must come from the seller or producer.
Does a Form 28 always lead to Form 29?
No. CBP may accept the explanation or continue its review. A Form 29 may follow when CBP proposes or takes an action affecting the entry, such as a change in classification, value, quantity or duty treatment.
Should the company answer questions that appear unrelated?
Do not ignore a question. Clarify the scope through the proper CBP contact and provide a precise response or explain why a request is not applicable. Qualified customs advice is appropriate where the scope is unclear.
Should related DDP shipments be stopped?
Not automatically. Review whether the same classification, value, origin, supplier or program claim appears in open or future entries. Apply appropriate holds or corrections based on the actual risk and professional advice.
Authoritative References
This article provides general operational information, not legal or customs advice. The importer should follow the specific notice, current CBP instructions and advice from a licensed customs broker or qualified customs counsel.
 English
 Deutsch
 Português
 العربية
 中文

 25 Sep